
Flat-rate amounts for 2026 published
In a letter dated 5 December 2025, the Federal Ministry of Finance (BMF) published the new flat-rate allowances for additional meal expenses and accommodation costs.
These regulations apply from 1 January 2026 to business trips abroad undertaken for professional or company-related reasons.
The flat-rate amounts set out in the BMF letter apply to:
-
business trips abroad undertaken by employees
-
business-related overseas trips undertaken by business owners
-
maintaining two households abroad
👉 Important:
For travel within Germany, the meal allowances remain unchanged. This means that the current rules for domestic travel will remain unchanged in 2026 as well.
🇩🇪 Meal allowances for 2026 in Germany (unchanged)
🇩🇪 Meal allowances for 2026 in Germany (unchanged)
| Absence | Flat rate |
|---|---|
| > 8 hours / journey to and from the venue | 14 € |
| 24 hours | 28 € |
| These amounts apply to business and work-related travel within Germany and may be claimed as income-related expenses or business expenses. Legal basis: Section 9(4a) of the Income Tax Act (EStG). |
🌍 New flat-rate allowances for work abroad from 1 January 2026
From 2026, country-specific flat-rate allowances will apply to travel abroad; these were revised by the Federal Ministry of Finance in December 2025. Changes compared with 2025 are highlighted in the official overview.
Key principles:
-
For one-day trips abroad, the flat-rate amount applicable to the last place of work applies.
-
For trips lasting several days, the following applies:
-
Day of arrival and departure: the flat-rate amount for the location reached before midnight local time
-
Intermediate days: the flat-rate allowance for the respective place of stay
-
The full list of countries can be found in the official annex to the BMF letter.
Reduction in the meal allowance for meals provided
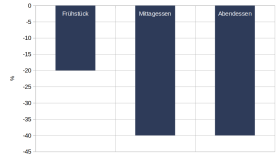
If meals are provided by the employer or at the employer’s instigation, the meal allowance must be reduced (Section 9(4a) of the Income Tax Act):
-
Breakfast: 20 per cent
-
Lunch: 40 per cent
-
Dinner: 40 per cent
The reduction is calculated on a daily basis, regardless of the country in which the meal was provided.
Accommodation costs in 2026: Important tax information
-
Flat-rate accommodation allowances may only be applied in the case of employer reimbursements.
-
For the purposes of deducting income-related expenses or business expenses, only the actual accommodation costs may be claimed.
-
Hotel bills and receipts must be kept.
This rule also applies to overnight stays abroad in the context of maintaining two households.
Who are the 2026 travel expense regulations relevant to?
Who are the 2026 travel expense regulations relevant to?
Travel expenses & overseas business trips:
- Employees on business trips abroad
- Self-employed and freelancers
- Companies with international operations
- HR and payroll departments
- Finance and tax departments
- Tax advisers and auditors
Mileage allowance (commuter scheme)
- Commuters
- Employees who commute to work daily
- Employer advisers and tax experts
- Payroll and remuneration accounting
Mileage allowance for business travel: No changes
The mileage allowance (also known as the business travel allowance) will remain unchanged at €0.30 per kilometre in 2026. This rate applies to all work-related journeys made in a private vehicle as part of business trips. Employers can reimburse this allowance to their staff tax-free without being required to provide detailed itemised evidence. This simplifies the reimbursement process and saves valuable time – particularly for companies, universities and hospitals that organise business trips on a regular basis.
Important: The mileage allowance applies exclusively to journeys undertaken in connection with business travel – such as visits to clients, trade fairs or other business appointments outside the employee’s primary place of work.
Note: The original version of this article discussed the distance allowance at this point. However, this has nothing to do with travel expense claims. See also our article "Travel Expenses 2026: Important Clarification"
Conclusion: Claiming travel expenses correctly in 2026
Conclusion: Claiming travel expenses correctly in 2026
From 1 January 2026, new flat-rate allowances will apply to additional meal expenses and accommodation costs for overseas travel. Whilst the domestic flat-rate allowances remain unchanged, companies and employees must take note of the updated overseas flat-rate allowances.
Correct implementation ensures:
-
tax certainty
-
travel expense claims that comply with the law
-
fewer queries during audits
Official source:
- Federal Ministry of Finance (BMF): ‘Tax treatment of travel expenses and travel allowances for business and work-related trips abroad from 1 January 2026’ dated 5 December 2025
- Income Tax Act (EStG): Section 9(4a) EStG – Additional meal expenses
- Wage Tax Guidelines (LStR): R 9.6 and R 9.7 LStR (travel expenses, accommodation costs)
- BMF letter dated 25 November 2020: Principles governing the tax treatment of travel expenses (still valid)
- Press and Information Office of the Federal Government: "Higher commuter allowance, lower VAT in the catering sector" dated 4 December 2025 (distance allowance)
For SaaS.de customers, the new flat-rate allowances for overseas travel will be implemented automatically. All changes will be managed by the SaaS.de team and correctly reflected in travel expense claims from 1 January 2026.